BCBSMA MyBlue Member App

Screenshots
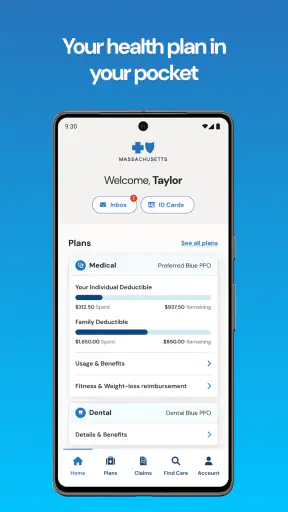
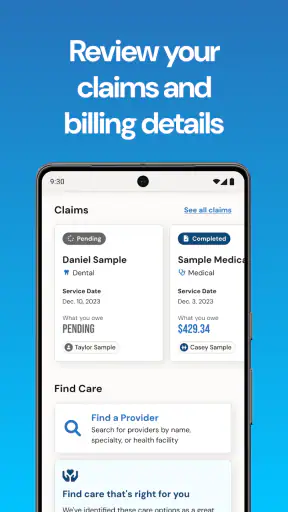
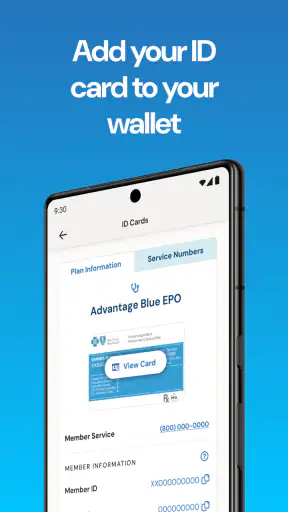
Details
- Rating
- 636.00 reviews
- Version
- 7.46
- Developer
- BCBSMA
Analysis by Norviv
When I review a medical app, I look at trust before convenience. Health coverage involves personal details, billing questions, appointments, and decisions that are stressful enough without adding uncertainty about where to tap or what an action will do. BCBSMA MyBlue is the member app from BCBSMA, designed for people covered by Blue Cross Blue Shield of Massachusetts. I found its value less in flashy extras and more in the possibility of keeping member-related tasks in one place.
That focus matters because this is not a general wellness tracker or a replacement for medical care. It belongs to the practical side of healthcare: the part where you need to understand your coverage, manage member information, and find the right next step. The app is free, available to Everyone, and has reached over 100 thousand installs, with a 4.7 average from around 1.9 thousand ratings. Those figures suggest that many members find it useful, although they do not remove the need to judge whether it fits your own plan and habits.
What I looked for before trusting it with member tasks
I approached BCBSMA MyBlue Member App as a tool for sensitive, account-based work. The developer shown for it is BCBSMA, which gives the app a clear connection to the insurer rather than making it look like an unrelated health service. That distinction is important when you are deciding where to enter or review insurance information.
The app has been available since June 2015, and its current version is 7.46. It supports operating systems from version 7.1 onward, so people using older compatible devices may still be able to install it. I would still keep the phone’s operating system and the app itself updated when possible, particularly for an application that handles an account connected to healthcare coverage.
My first practical test with any member app is whether it helps me answer a simple question without sending me through a maze: “What do I need to do next?” A good experience should make the difference between checking information, changing an account setting, and contacting support reasonably clear. I also pay attention to whether the app gives me a chance to review an action before committing to it. Those small moments are where trust is built.
There is a useful boundary here. An insurer’s app can organize coverage-related work, but it cannot turn an uncertain medical situation into a simple administrative task. If I had urgent symptoms, I would not open a member app first. I would use appropriate medical help. The app makes more sense for the paperwork and coverage side of healthcare, not for diagnosis or emergency decisions.
Why the account context matters
Many healthcare apps look similar at a glance, but the provider behind the account changes the experience. A general health app may be good for tracking habits, while a hospital app may focus on appointments and clinical records. BCBSMA MyBlue is aimed at members of one insurer, so its usefulness depends heavily on whether your coverage is through Blue Cross Blue Shield of Massachusetts.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
That is also the main reason I would not recommend installing it simply because it has a strong rating. The rating reflects the experience of people who use this specific insurance service, not a universal assessment for every patient. If your plan belongs to another insurer, this is not a substitute for that insurer’s official member tools.
For an eligible member, the advantage is continuity. Instead of treating insurance as a stack of letters, cards, and separate browser bookmarks, the app can become a regular point of access. I would use it when I want to start with my member account rather than search the wider web and risk landing on an unofficial page.
Trust is also about visible choices
When I assess a health-related app, I do not assume that a familiar brand makes every screen automatically trustworthy. I look for clear account entry, understandable labels, and actions that do not feel hidden. I also want to know when the app is asking me to move from viewing information to sharing, submitting, or changing something.
That is the standard I would apply while using this app: pause before confirming a request, check the destination of any message or document, and avoid entering sensitive details on a device that other people use without a separate protected profile. These are not glamorous tips, but they are more useful than treating an app rating as a security guarantee.
I would also review the phone’s permission controls during installation and after major updates. Permissions should be considered individually, not accepted automatically. If a request does not make sense for the task I am trying to complete, I would stop and investigate through the official support route rather than guessing. The important point is that trust should come from visible choices and informed use, not from assumptions about what an app must be doing in the background.
Using it when healthcare paperwork becomes urgent
A realistic example is a weekday morning when I am preparing for a medical visit and realize I need insurance information. I do not want to search old email, photograph a card, or call a number without knowing what question to ask. I would open the member app, sign in carefully, and use it as the starting point for checking the relevant account information.
The best workflow in that situation is deliberate rather than rushed. I would confirm that I am in the correct account, read the wording on the screen, and save only what I genuinely need. If I were using a shared tablet or a family member’s phone, I would be especially cautious about leaving the session open. On a personal phone, I would still lock the device and avoid displaying member details in public.
Another useful situation is handling an administrative question after receiving a bill. I would first separate the bill itself from the insurance question. The app may be the right place to begin understanding member-related information, but I would not assume that every amount on a provider bill can be resolved inside the app. If the issue involves a medical office, a claim, or a payment, I would read the labels carefully and contact the appropriate party rather than sending the same question repeatedly through different channels.
This is one of the less obvious trade-offs of a focused insurer app: it can reduce confusion when the question belongs to the insurer, but it cannot remove the boundaries between insurer, provider, and patient. I find that useful because it encourages me to identify who actually controls the information before I share more personal details.
Account controls deserve more attention than the home screen
People often judge an app by how quickly it opens, but account controls matter more in a medical setting. I would look for the sign-out option, account profile details, contact preferences, and any available way to review or change how the account is used. I would also check whether the app makes it obvious when I am viewing information versus submitting a request.
Before handing my phone to someone else, I would sign out if the app allows it and close any visible account screen. I would not rely only on the phone’s lock screen, especially if another person knows the device passcode. If I changed phones, I would treat the old device as a separate security task: remove access where appropriate, delete stored app data if needed, and make sure the new device is the one I intend to use.
These habits are particularly important for family situations. A parent may help an older relative with technology, or a partner may manage household paperwork. Assistance is reasonable, but shared access should be intentional. I would avoid saving credentials in a place where another person can use them accidentally, and I would make sure the account holder understands what is being viewed or submitted.
I also prefer to review notifications instead of allowing every alert to appear in full on the lock screen. A notification that reveals account context can be uncomfortable in a workplace, clinic waiting room, or shared home. If the phone offers notification privacy settings, I would use them. This is a simple way to preserve control without abandoning the convenience of reminders altogether.
What happens during data-sensitive moments
The most sensitive moments are not necessarily the login screen. They include searching for coverage information in a public place, composing a message, downloading or viewing a document, and deciding whether to share a screen with a provider or family member. I would slow down during each of these moments and check exactly what is visible.
For example, if I were at a clinic and needed to show information from the app, I would open only the relevant screen instead of handing over the unlocked phone. I would keep other account pages closed and take the phone back as soon as the task was complete. If I needed to record information for later, I would avoid placing full member details in an unprotected notes app unless there was a clear reason.
I would apply the same care to screenshots. A screenshot can be convenient for remembering a reference, but it can also remain in the phone’s photo library, cloud backup, or shared album. I would use one only when necessary, then remove it from all likely locations. That workflow is more cautious than simply assuming that an in-app screen disappears when I navigate away.
Another trade-off is convenience versus verification. A quick tap may save time, but healthcare information is not the right place to guess. If a label is unclear, I would read the surrounding text, check the account context, and use an official support option. I would not rely on a social media comment or an unofficial number found through a random search to resolve an account issue.
Where this app fits beside the usual alternatives
Compared with calling an insurer, a member app can be more comfortable for people who prefer to review information quietly and outside business hours. It also gives me a written screen to inspect, which can be easier than remembering a long phone conversation. That said, a phone representative may be better when the situation is complicated, urgent, or too ambiguous to resolve through menus.
Compared with a mobile browser, a dedicated app can feel more direct because it keeps the member service separate from unrelated tabs and search results. A browser may still be preferable on a shared or temporary device, where installing an account app creates extra cleanup work. I would choose the browser when I need one short task and do not expect to use the service regularly.
Compared with a hospital or doctor-office app, this one belongs to a different layer of the healthcare journey. A provider’s app may be the better place for clinical communication or office-specific scheduling, while an insurer’s member app is the logical starting point for coverage administration. I would not expect one to replace the other.
Compared with a general health tracker, the distinction is even clearer. A tracker can help with habits, exercise, or measurements, but it does not serve the same insurance purpose. I would choose BCBSMA MyBlue when the question is tied to my Blue Cross Blue Shield of Massachusetts membership, and a different health tool when I want personal wellness tracking.
Who will benefit, and who should skip it
I think the app is best for current members who regularly manage their own coverage and want a mobile entry point instead of relying on paper documents or phone calls. It can also suit someone who wants to check account-related information before contacting support, provided they are comfortable signing in and reading administrative language carefully.
It is less suitable for people who are not members of the relevant Blue Cross Blue Shield organization. It is also not the right choice for someone looking for medical diagnosis, emergency guidance, medication management, or a broad fitness platform. Installing it will not solve a clinical problem simply because the subject is healthcare.
I would also hesitate to recommend an app-first approach to someone who struggles with small text, account passwords, or digital forms unless a trusted helper is available. A phone call or in-person assistance may be less frustrating. The strongest tool is the one that lets the user understand what is happening and stay in control, not necessarily the newest format.
For privacy-conscious users, my recommendation is conditional rather than automatic. Use it on a personal, updated device; review permissions and notifications; sign out when appropriate; and avoid storing unnecessary screenshots or credentials. Those steps do not prove anything about the app’s internal data handling, but they do reduce avoidable exposure on the user’s side.
My cautious verdict after weighing convenience and control
BCBSMA MyBlue makes sense as a focused member service for people covered by Blue Cross Blue Shield of Massachusetts. Its free price, Everyone age rating, established release history, and current version make it accessible to a broad range of eligible users. The 636 written reviews and strong average rating add useful context, but I would still judge it by whether it makes my own insurance tasks clearer.
What I appreciate most is the defined purpose. I am not opening it for entertainment or vague health advice; I am opening it because I need to deal with the member side of healthcare. That narrow role can be a strength, especially when I want to avoid mixing insurance work with unrelated wellness apps or unofficial websites.
My reservation is that convenience can encourage careless behavior. A member app puts sensitive information close at hand, so I would not leave it permanently open, share screens casually, or approve every device request without reading it. I would also switch to a phone representative or the appropriate healthcare provider when the issue crosses into a complicated claim, clinical question, or unclear responsibility.
In the end, I would recommend it to an eligible member who wants a practical mobile starting point and is willing to manage account access thoughtfully. I would not recommend it as a universal healthcare companion. The safest experience comes from combining the app’s convenience with deliberate choices about access, visibility, and who should receive each piece of information.
That is why my verdict is positive but measured. BCBSMA MyBlue can make routine member administration easier, particularly when I need information while away from home. Its real value depends on matching the task to the insurer’s role, checking each screen before acting, and remembering that digital access is helpful only when the person using it remains in control.
Frequently Asked Questions
01What is the BCBSMA MyBlue Member App used for?
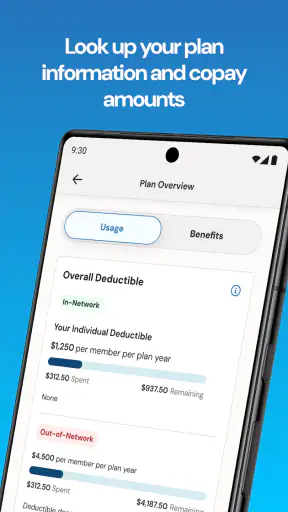
The BCBSMA MyBlue Member App is designed for members of Blue Cross Blue Shield of Massachusetts to manage health insurance information from a mobile device. After signing in, members can typically view plan details, access digital ID cards, review claims and benefits, search for in-network doctors or facilities, and find contact options for member support. Available features may depend on your specific plan.
02Who can use the BCBSMA MyBlue Member App?
The app is intended for eligible Blue Cross Blue Shield of Massachusetts members, including members whose employer or individual plan provides access to MyBlue services. You generally need an active member account and valid login credentials. Dependents may have different access rules, and some users could be directed to create or verify an online account before using the app’s member features.
03Can I use the app to show my health insurance ID card?
Yes, one of the most practical features is access to a digital member ID card, allowing you to present coverage information at a doctor’s office, pharmacy, or other participating provider without carrying a physical card. It is still wise to keep a physical card available when possible, especially if your phone battery is low, you have limited connectivity, or the provider cannot accept a digital version.
04Can I find doctors, hospitals, and other in-network providers through the app?
The MyBlue Member App generally includes tools for locating providers and healthcare facilities within your plan’s network. Search results may be filtered by specialty, location, services, or other criteria. Before scheduling care, review the provider’s network status and confirm details directly with the office, because participation, availability, referrals, and out-of-pocket costs can vary by plan and may change over time.
05Is the BCBSMA MyBlue Member App free, and is my information secure?
The app is normally available to eligible members at no additional download cost, although your insurance plan remains subject to its own premiums, deductibles, copayments, and other charges. Access requires secure account authentication, and the app may use safeguards such as password protection, device security, and encrypted communication. Always install it from an official app store and avoid sharing your login details.


